Sensible_investments_with_https_thorfortunes_ca_empower_future_financial_securit
- Sensible investments with https://thorfortunes.ca empower future financial security today
- Understanding Your Investment Horizon
- The Importance of Asset Allocation
- Risk Management and Portfolio Protection
- Strategies for Mitigating Downside Risk
- The Role of Professional Financial Advice
- Questions to Ask a Potential Financial Advisor
- Long-Term Financial Planning and Retirement
- Navigating Market Volatility and Staying the Course
Sensible investments with https://thorfortunes.ca empower future financial security today
Navigating the complexities of modern financial planning requires a thoughtful and proactive approach. Many individuals find themselves overwhelmed by the sheer number of investment options and the ever-changing economic landscape. Securing a comfortable future isn’t simply about earning a substantial income; it’s about making informed decisions that allow your wealth to grow and withstand potential challenges. A key element of this process is identifying reliable partners who can offer guidance and support. Exploring options like those available at https://thorfortunes.ca can be a significant step towards achieving long-term financial stability.
The concept of sensible investment is rooted in understanding risk tolerance, setting realistic goals, and diversifying portfolios. It’s not about chasing the highest returns, but rather about building a strategy that aligns with your individual circumstances and aspirations. Considerations should extend beyond simply maximizing profit and encompass factors such as tax efficiency, inflation, and the potential for unforeseen expenses. Building a solid financial foundation requires discipline, consistent effort, and a commitment to ongoing learning. This proactive mindset, combined with expert guidance, can empower individuals to take control of their financial destiny.
Understanding Your Investment Horizon
One of the first steps in any investment strategy is to define your investment horizon. This refers to the length of time you plan to hold onto your investments before needing to access the funds. A longer investment horizon generally allows for greater risk-taking, as there is more time to recover from potential market downturns. Conversely, a shorter horizon necessitates a more conservative approach to preserve capital. Factors influencing your investment horizon include your age, financial goals, and anticipated expenses. For instance, someone saving for retirement decades away can afford to allocate a larger portion of their portfolio to growth-oriented assets, such as stocks. However, someone saving for a down payment on a house in the next few years should prioritize stability and liquidity.
The Importance of Asset Allocation
Once you’ve determined your investment horizon, the next crucial step is asset allocation. This involves dividing your portfolio among different asset classes, such as stocks, bonds, and real estate. The goal is to create a diversified portfolio that can deliver optimal returns while minimizing risk. Different asset classes perform differently under various market conditions. For example, stocks tend to offer higher potential returns but also carry greater volatility, while bonds are generally considered more stable but offer lower returns. The optimal asset allocation will vary depending on your individual circumstances and risk tolerance. A financial advisor can help you determine the appropriate mix of assets for your portfolio. Diversification doesn’t guarantee against loss, but it can help to cushion the impact of market fluctuations.
Effective asset allocation extends beyond simply dividing your money among stocks and bonds. It can include considering international investments, different sectors within each asset class, and even alternative investments like commodities or private equity. Rebalancing your portfolio periodically is also essential. Over time, certain assets will outperform others, causing your original asset allocation to drift. Rebalancing involves selling some of the overperforming assets and buying more of the underperforming ones to restore your desired allocation. This helps to maintain your risk profile and potentially improve long-term returns.
| Stocks | High | High | Long-term growth, younger investors |
| Bonds | Low to Moderate | Moderate | Income generation, capital preservation |
| Real Estate | Moderate to High | Moderate to High | Diversification, long-term appreciation |
| Commodities | Moderate to High | Variable | Inflation hedge, diversification |
Understanding the nuances of each asset class and their potential roles within a diversified portfolio is paramount. It is advisable to consult with a financial professional who can provide tailored guidance based on your specific financial situation and objectives.
Risk Management and Portfolio Protection
Investment inherently involves risk, and understanding and managing that risk is crucial for long-term success. Risk tolerance varies significantly from person to person, and it’s essential to assess your comfort level with potential losses before making any investment decisions. Common types of investment risk include market risk, inflation risk, and liquidity risk. Market risk refers to the possibility of losing money due to fluctuations in the overall market. Inflation risk is the risk that the purchasing power of your investments will be eroded by rising prices. Liquidity risk is the risk that you won’t be able to sell your investments quickly enough to meet your financial obligations. Proactive risk management involves diversification, setting appropriate stop-loss orders, and regularly reviewing your portfolio.
Strategies for Mitigating Downside Risk
Several strategies can help mitigate downside risk. Diversification, as previously mentioned, is fundamental. Investing in a variety of asset classes reduces your exposure to any single risk factor. Another strategy is to use stop-loss orders, which automatically sell your investments if they fall below a certain price level. This can help to limit your losses during a market downturn. Dollar-cost averaging, which involves investing a fixed amount of money at regular intervals, can also help to reduce risk by averaging out your purchase price over time. Furthermore, maintaining an emergency fund can provide a financial buffer during unexpected events, reducing the need to sell investments at unfavorable times. Seeking advice from professionals at a reputable firm like https://thorfortunes.ca can offer a tailored plan.
Beyond these specific techniques, a fundamental principle of risk management is to avoid emotional decision-making. Market fluctuations are inevitable, and reacting impulsively to short-term movements can often lead to poor investment outcomes. Instead, it’s important to remain focused on your long-term goals and stick to your pre-determined investment strategy. Remember that investing is a marathon, not a sprint.
- Diversify your portfolio across multiple asset classes.
- Utilize stop-loss orders to limit potential losses.
- Implement dollar-cost averaging for consistent investments.
- Maintain an adequate emergency fund for unexpected expenses.
- Avoid making emotional investment decisions.
Remember, consistent risk management is an ongoing process, not a one-time event. Regularly review your portfolio, reassess your risk tolerance, and adjust your strategy as needed.
The Role of Professional Financial Advice
While self-directed investing is possible, many individuals benefit from seeking the guidance of a qualified financial advisor. A financial advisor can provide personalized advice tailored to your unique circumstances, help you develop a comprehensive financial plan, and manage your investments on your behalf. The benefits of working with a financial advisor include access to expertise, objective advice, and a disciplined investment process. A good advisor will take the time to understand your goals, risk tolerance, and time horizon before recommending any specific investments. They will also monitor your portfolio regularly and make adjustments as needed. Selecting a qualified advisor involves researching their credentials, experience, and fee structure.
Questions to Ask a Potential Financial Advisor
Before engaging a financial advisor, it’s important to ask some key questions to ensure they are the right fit for your needs. These questions should include their qualifications and certifications, their experience working with clients in similar situations, their investment philosophy, and their fee structure. It’s also important to understand how they are compensated—whether they charge a fee based on assets under management, commissions, or a combination of both. Transparency is key; a reputable advisor will be happy to answer your questions and provide clear explanations of their services and fees. Additionally, you should inquire about their process for handling conflicts of interest and their commitment to acting in your best interest. Services similar to those at https://thorfortunes.ca should be thoroughly vetted.
- What are your qualifications and certifications?
- What experience do you have with clients similar to me?
- What is your investment philosophy?
- How are you compensated?
- What is your process for handling conflicts of interest?
- How often will we review my portfolio?
- What is your communication style?
Taking the time to find a trustworthy and competent financial advisor can be a significant investment in your financial future.
Long-Term Financial Planning and Retirement
Investing isn’t just about short-term gains; it’s about building a secure financial future, particularly for retirement. Long-term financial planning involves setting realistic goals, creating a budget, and saving consistently over time. Retirement planning is a particularly important aspect of this process. It requires estimating your future expenses, determining how much you’ll need to save to achieve your desired lifestyle, and choosing the right investment vehicles to help you reach your goals. Considerations for retirement planning include Social Security benefits, pension plans, and the tax implications of different investment accounts. Starting early is crucial, as the power of compounding can significantly enhance your long-term returns.
Furthermore, a comprehensive retirement plan should also address potential healthcare costs, long-term care needs, and estate planning considerations. Healthcare expenses tend to rise as people age, and planning for these costs is essential to avoid depleting your savings. Long-term care insurance can help cover the costs of assisted living or nursing home care. Estate planning involves creating a will, establishing trusts, and making arrangements for the distribution of your assets after your death. A well-thought-out estate plan can help to ensure that your wishes are carried out and that your loved ones are protected. A solid plan, like those developed with guidance from a firm such as https://thorfortunes.ca, can provide peace of mind.
Navigating Market Volatility and Staying the Course
Market volatility is an inherent part of investing. There will be periods of both growth and decline, and it’s crucial to remain disciplined and avoid making rash decisions based on short-term market fluctuations. Trying to time the market—buying low and selling high—is notoriously difficult, and often leads to suboptimal results. Instead, it’s generally more effective to adopt a long-term perspective and stay invested through both the good times and the bad. Remember that market downturns can present opportunities to buy assets at lower prices. However, it’s important to do your research and ensure that any investments you make align with your overall financial goals and risk tolerance. Focusing on fundamentally sound investments, maintaining a diversified portfolio, and avoiding emotional decision-making are key to navigating market volatility successfully.
The ability to remain calm and focused during periods of market turbulence is a hallmark of a successful investor. It requires emotional resilience, a clear understanding of your investment strategy, and a commitment to long-term goals. Instead of panicking during market downturns, view them as potential opportunities to rebalance your portfolio or add to your existing positions. Regularly reviewing your financial plan and making adjustments as needed can also help you stay on track and weather any storms that may come your way. Ultimately, long-term investing success is about consistency, discipline, and a well-defined plan.

Top rated products
-
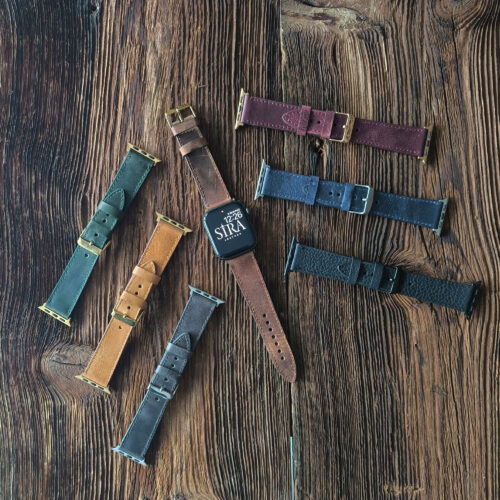 2003-L-AppleWatchStrap
Orijinal fiyat: $59.00.$46.50Şu andaki fiyat: $46.50.
-
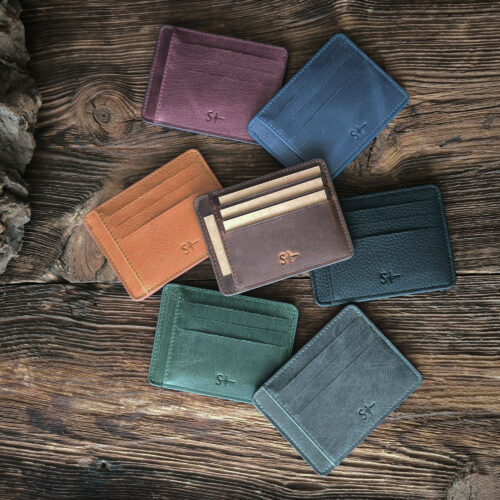 4008-L-CardHolder-ROYAL
$21.00
-
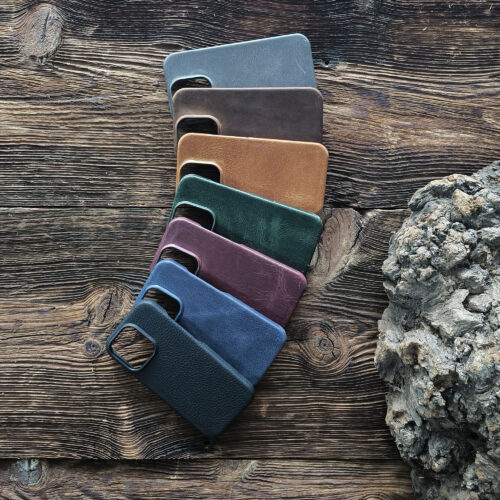 1001-L-PhoneCase-FLAT
Orijinal fiyat: $39.90.$34.90Şu andaki fiyat: $34.90.
-
 3001-L-GlassesCase1-BUTTON
$20.50
-
 4008-Z-CardHolder-CACHE-ZIPPO
$25.00